
SeanVega Trading
A running archive of US10Y (U.S. 10-Year Treasury Yield) views from Tactical Positioning.
Drag, or hold Alt and press the left or right arrow, to reorder within a group. Publications you write for stay ahead of subscriptions. Changes save automatically.
A running archive of US10Y (U.S. 10-Year Treasury Yield) views from Tactical Positioning.
US10Y · —Yields continue to rise alongside Gold and Silver. Warning signs cannot be more dire.
US10Y · —I warned about long-end yields exploding to the upside back in 25Q4, and they're set to only grind higher.
US10Y · —And this is not just the U.S. We have seen a sharp rise in 10y yields globally since the Iran conflict began, with the U.K. +53bp, Canada +38bp, Germany +32bp, Italy +52bp, Japan +12bp, Australia +30bp, South Korea +23bp, Brazil +88bp, South Africa +96bp, Mexico +48bp, and France +45bp.
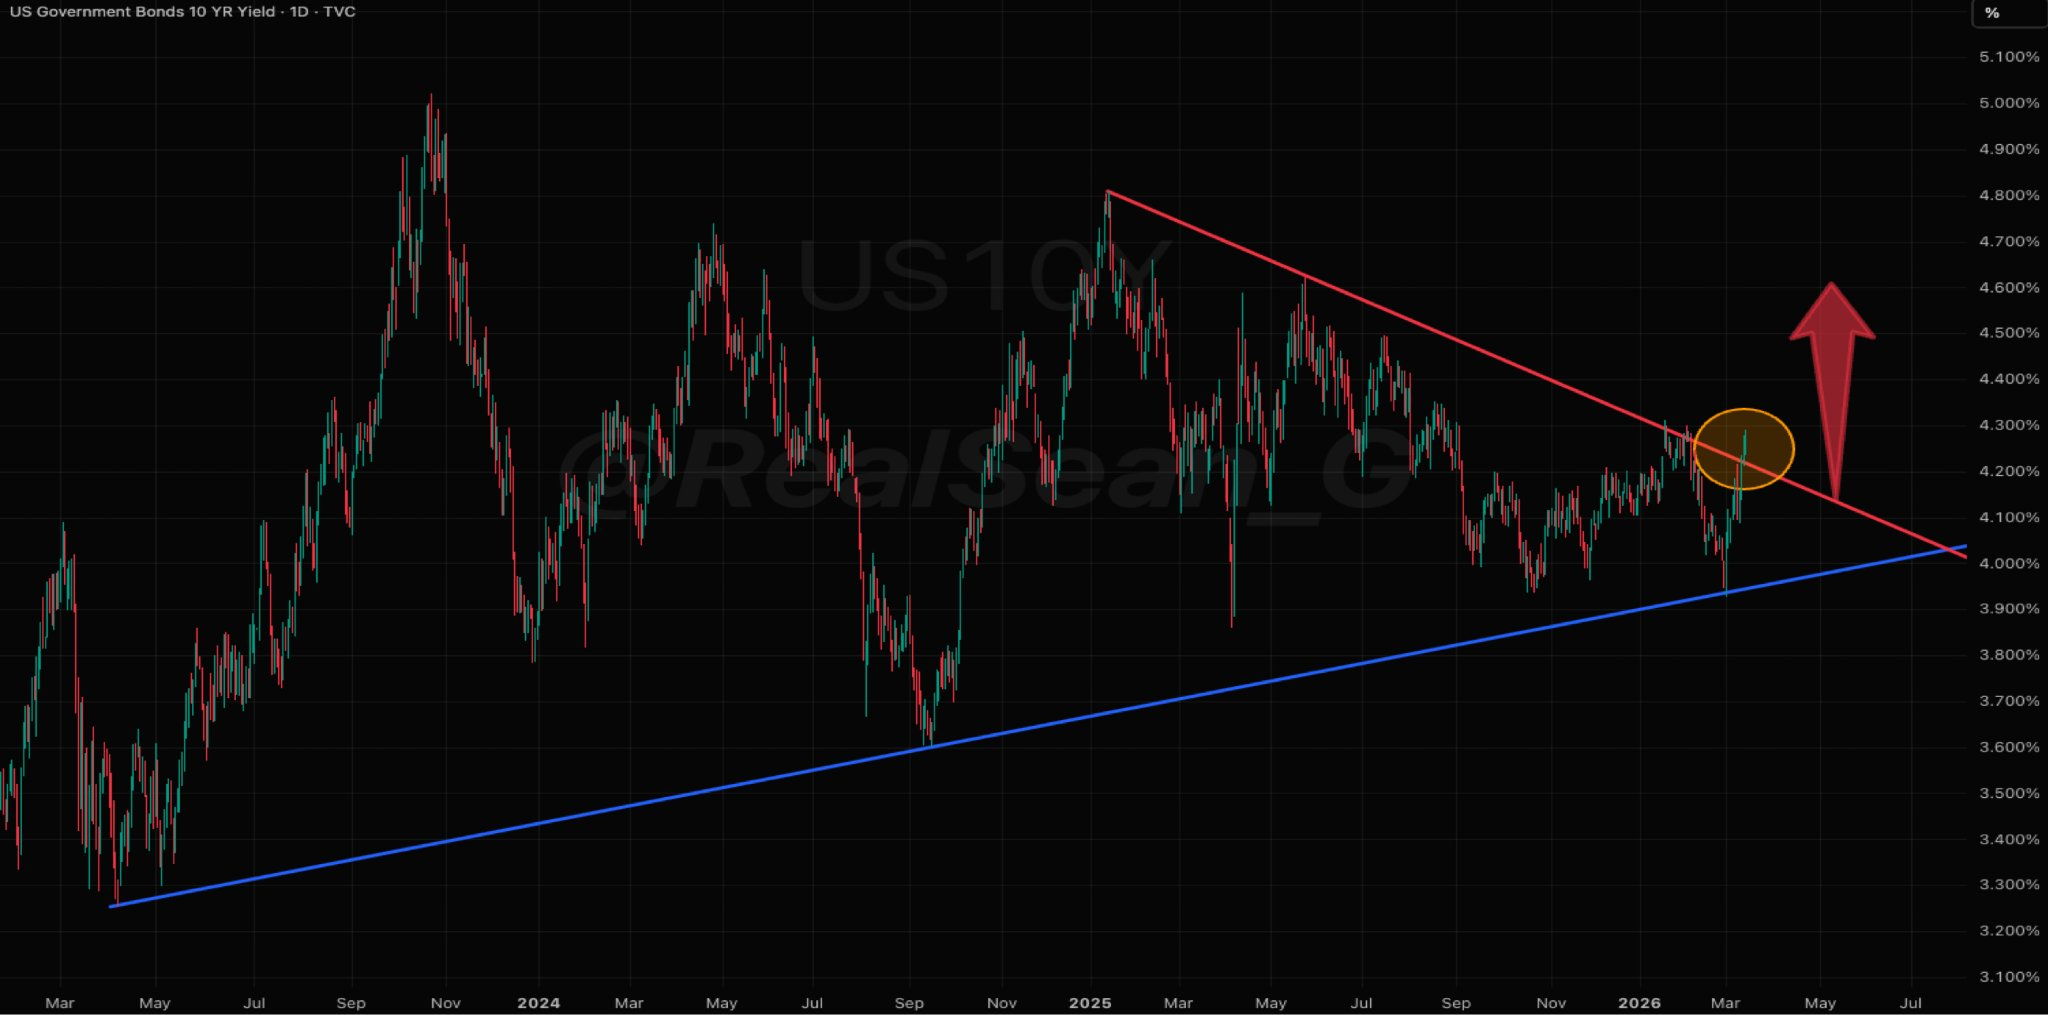
US10Y · —Yields worldwide continue to explode to the upside, as I expected. Higher oil prices for longer -> higher inflation expectations -> higher long-end yields -> lower equity multiples, especially for long-duration names such as the M7, including your favorite, NVDA (Nvidia).
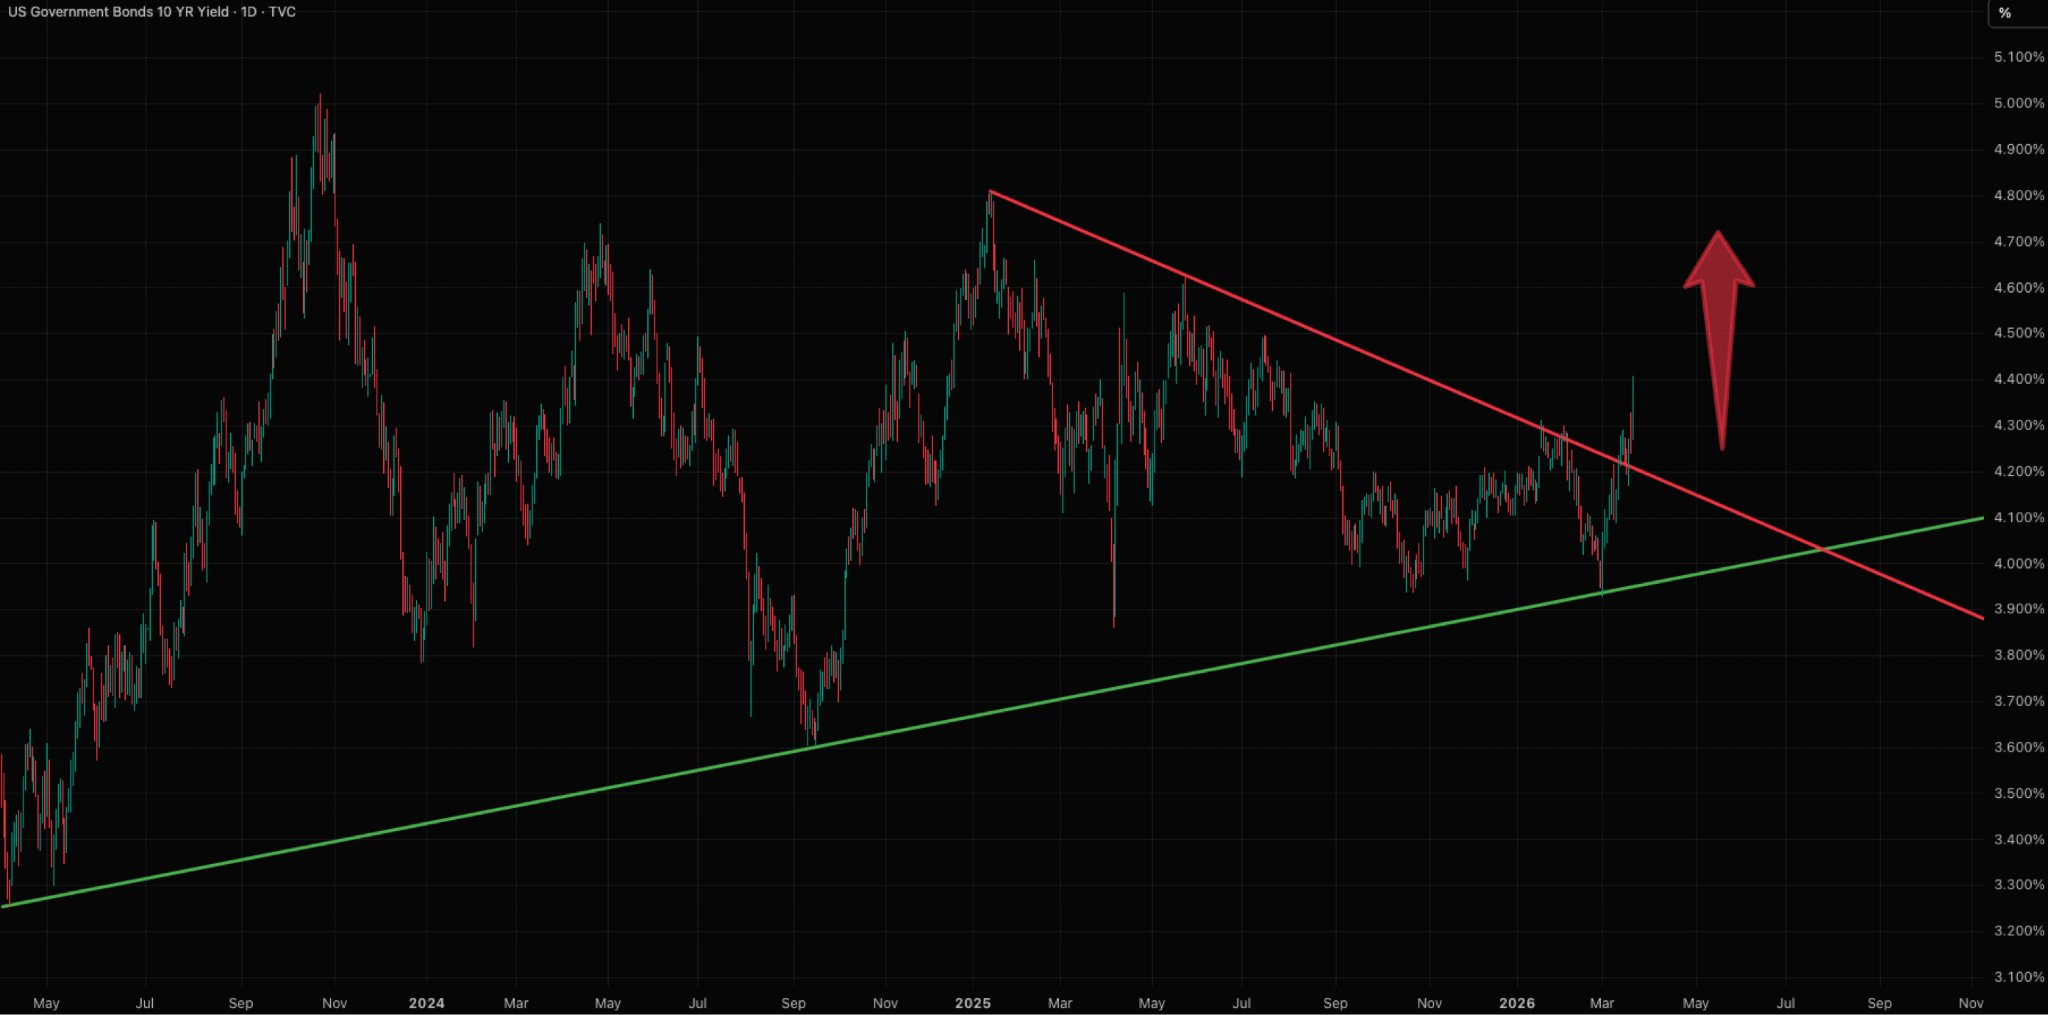
US10Y · —Yields worldwide continue to explode to the upside, as I expected. Higher oil prices for longer -> higher inflation expectations -> higher long-end yields -> lower equity multiples, especially for long-duration names such as the M7. As long as the war continues and the Strait of Hormuz is not back in business, we should expect higher oil prices and higher yields across the globe.
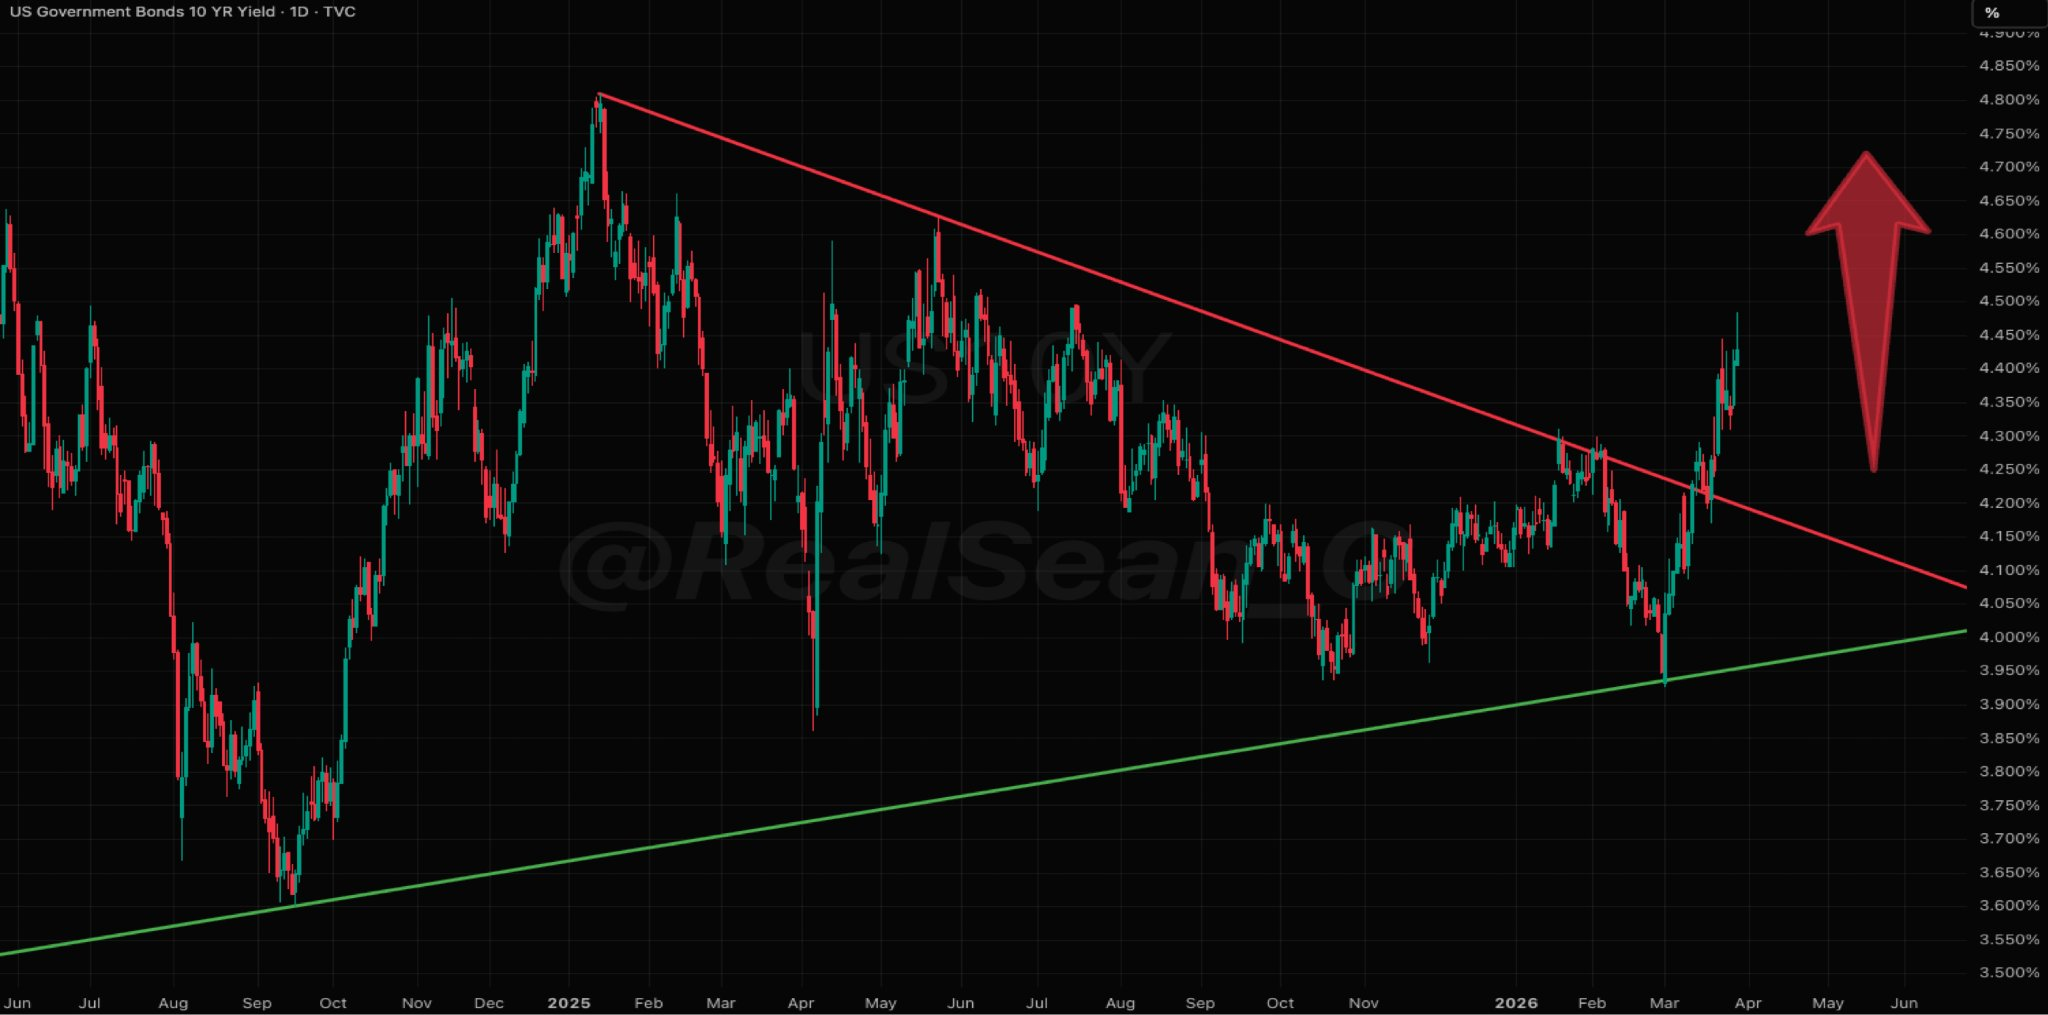
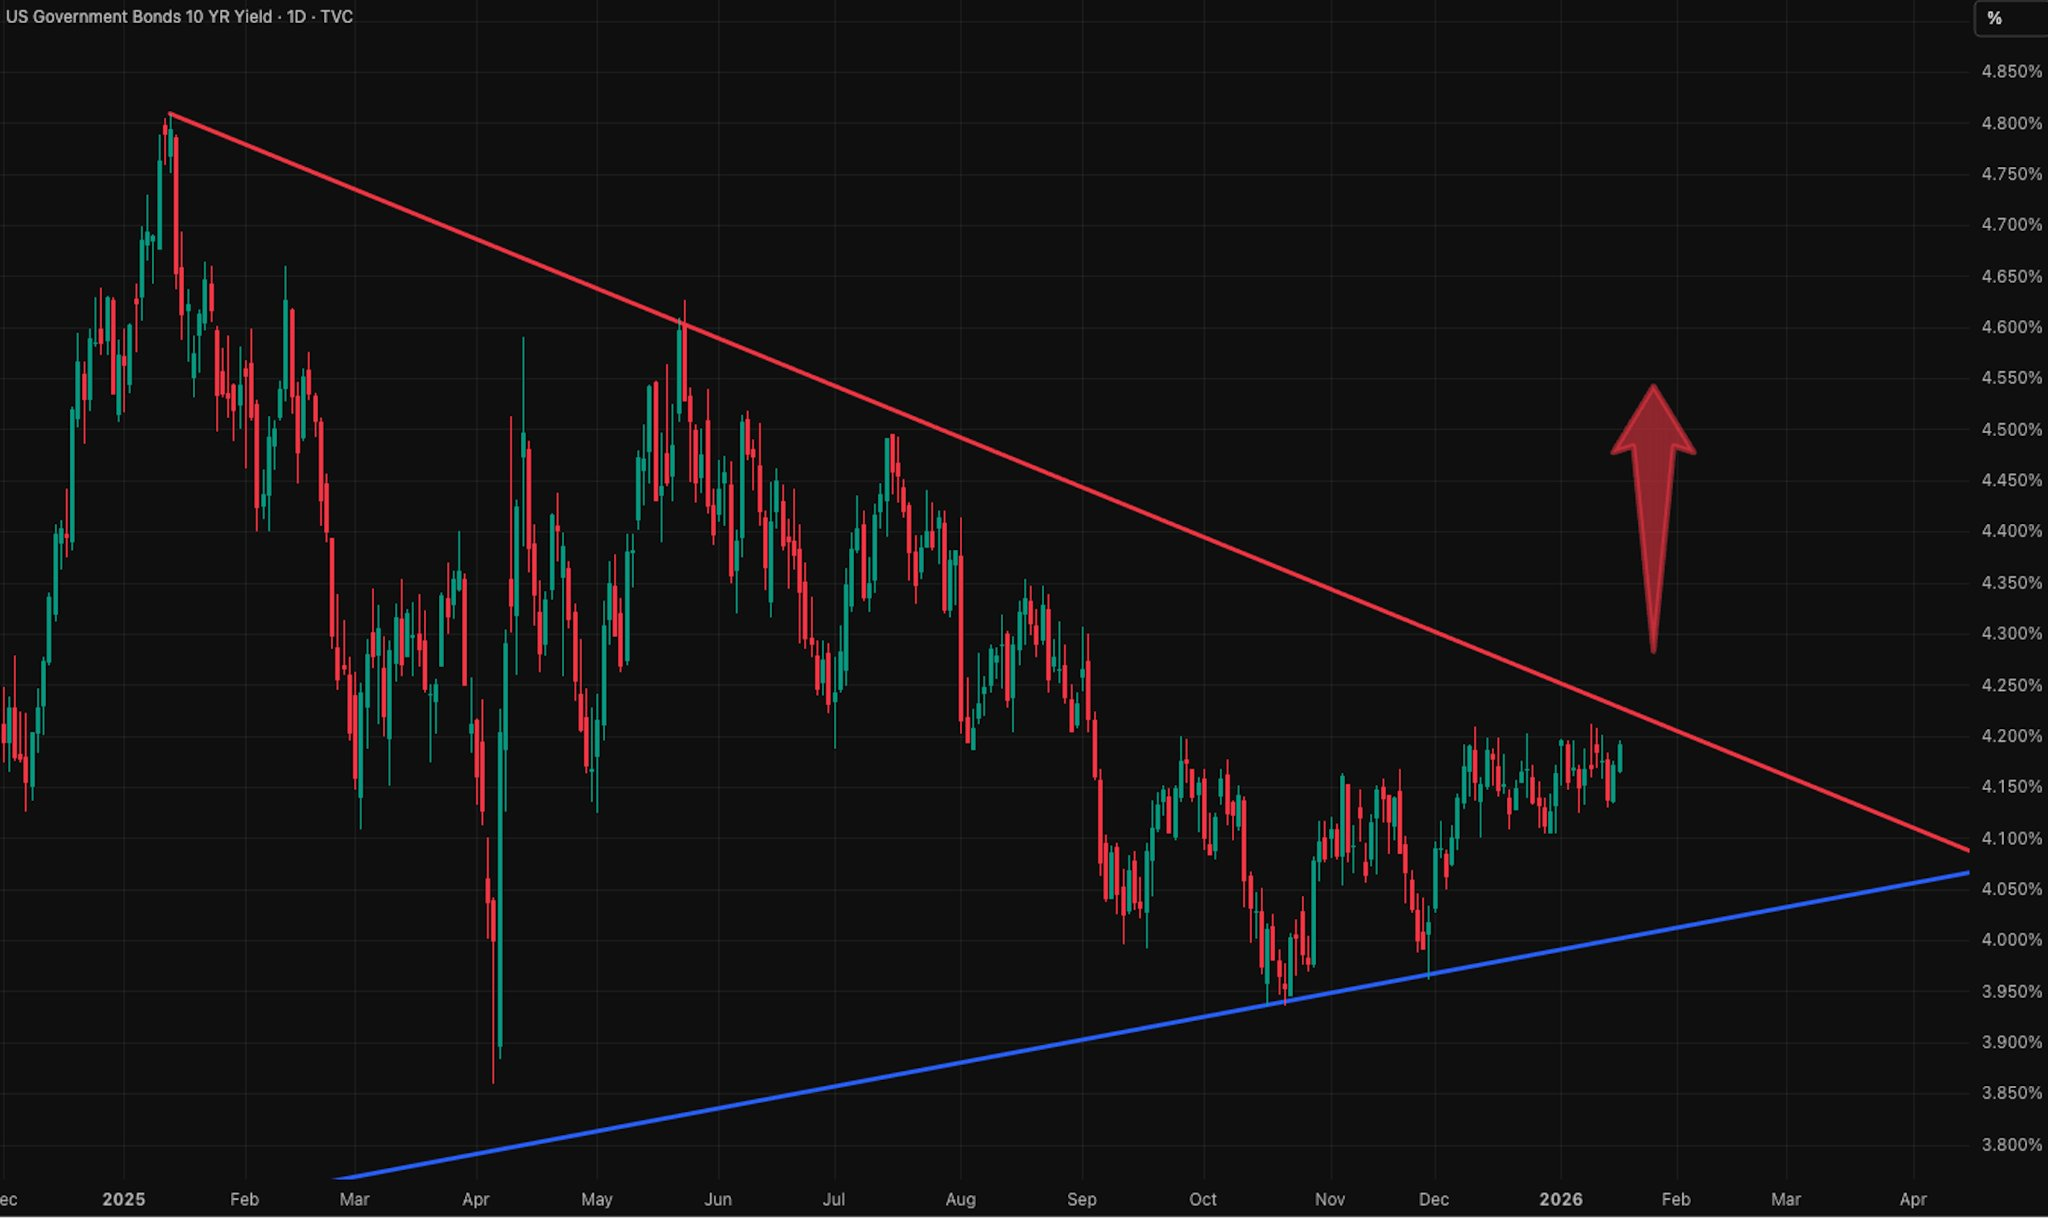
US10Y · —Unless US10Y (U.S. 10-Year Treasury Yield) moves back inside the triangle, momentum remains to the upside.
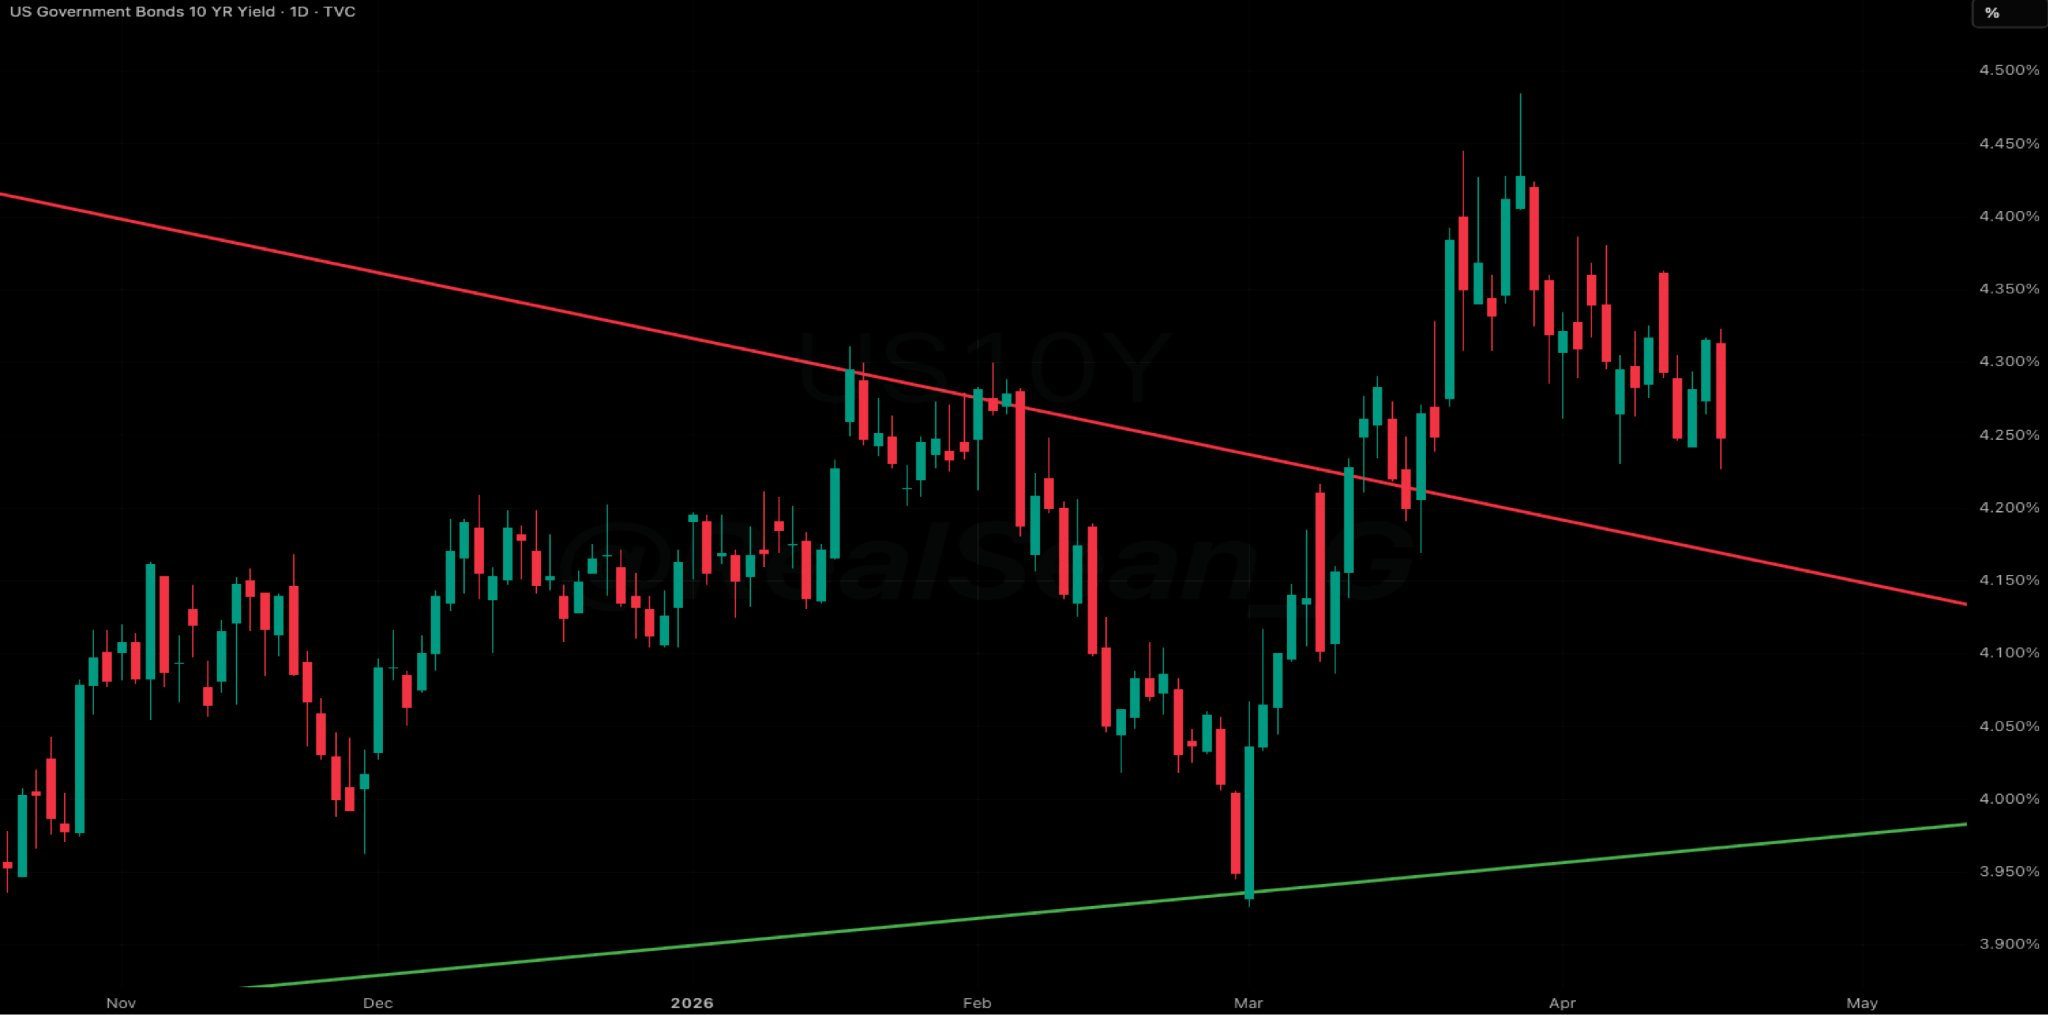
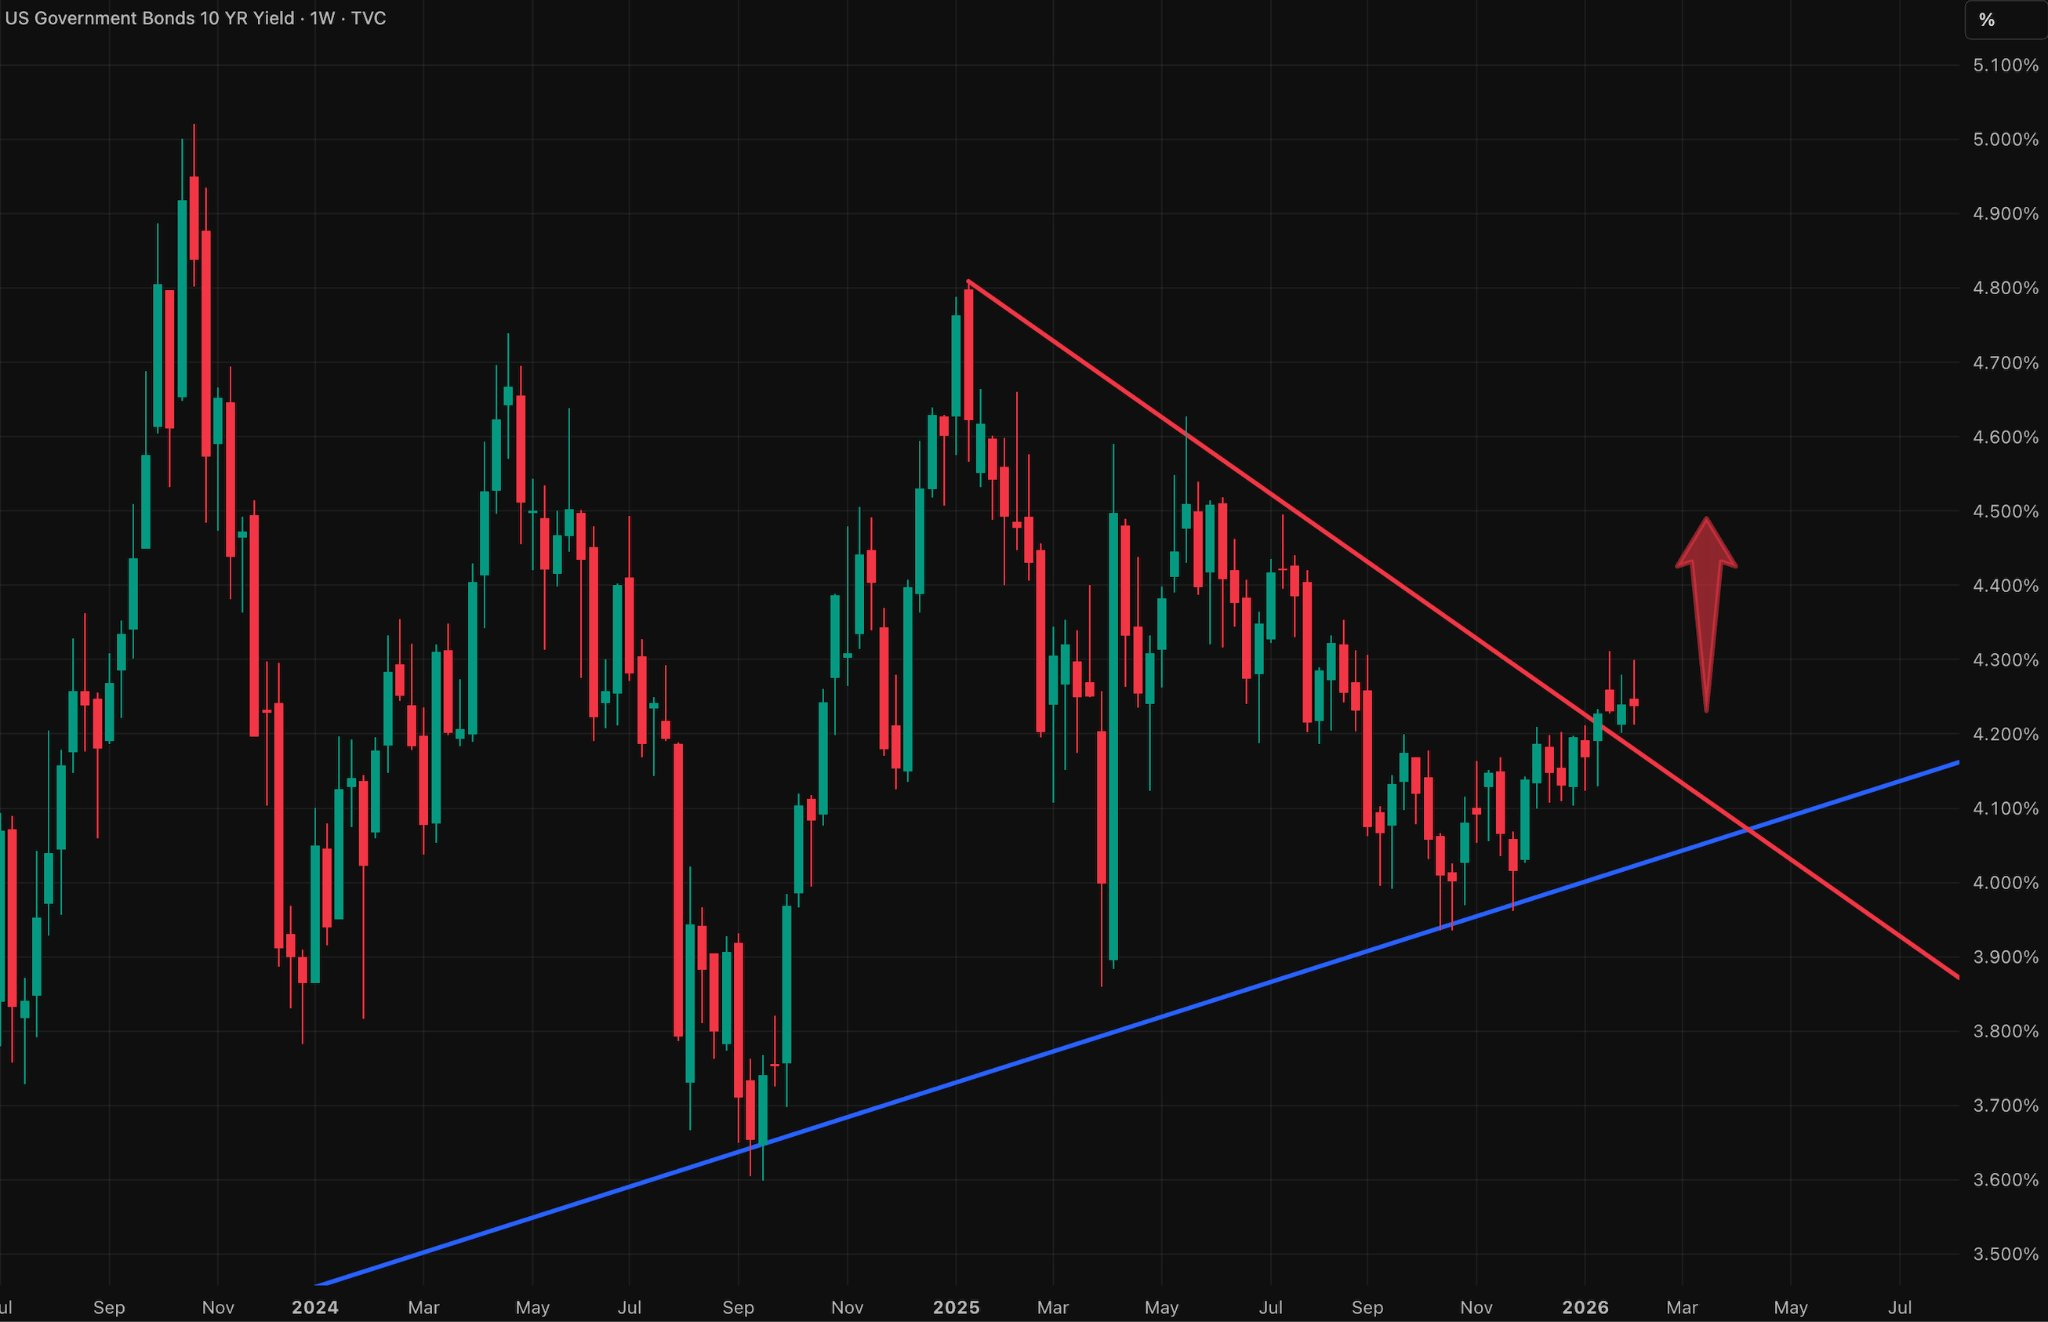
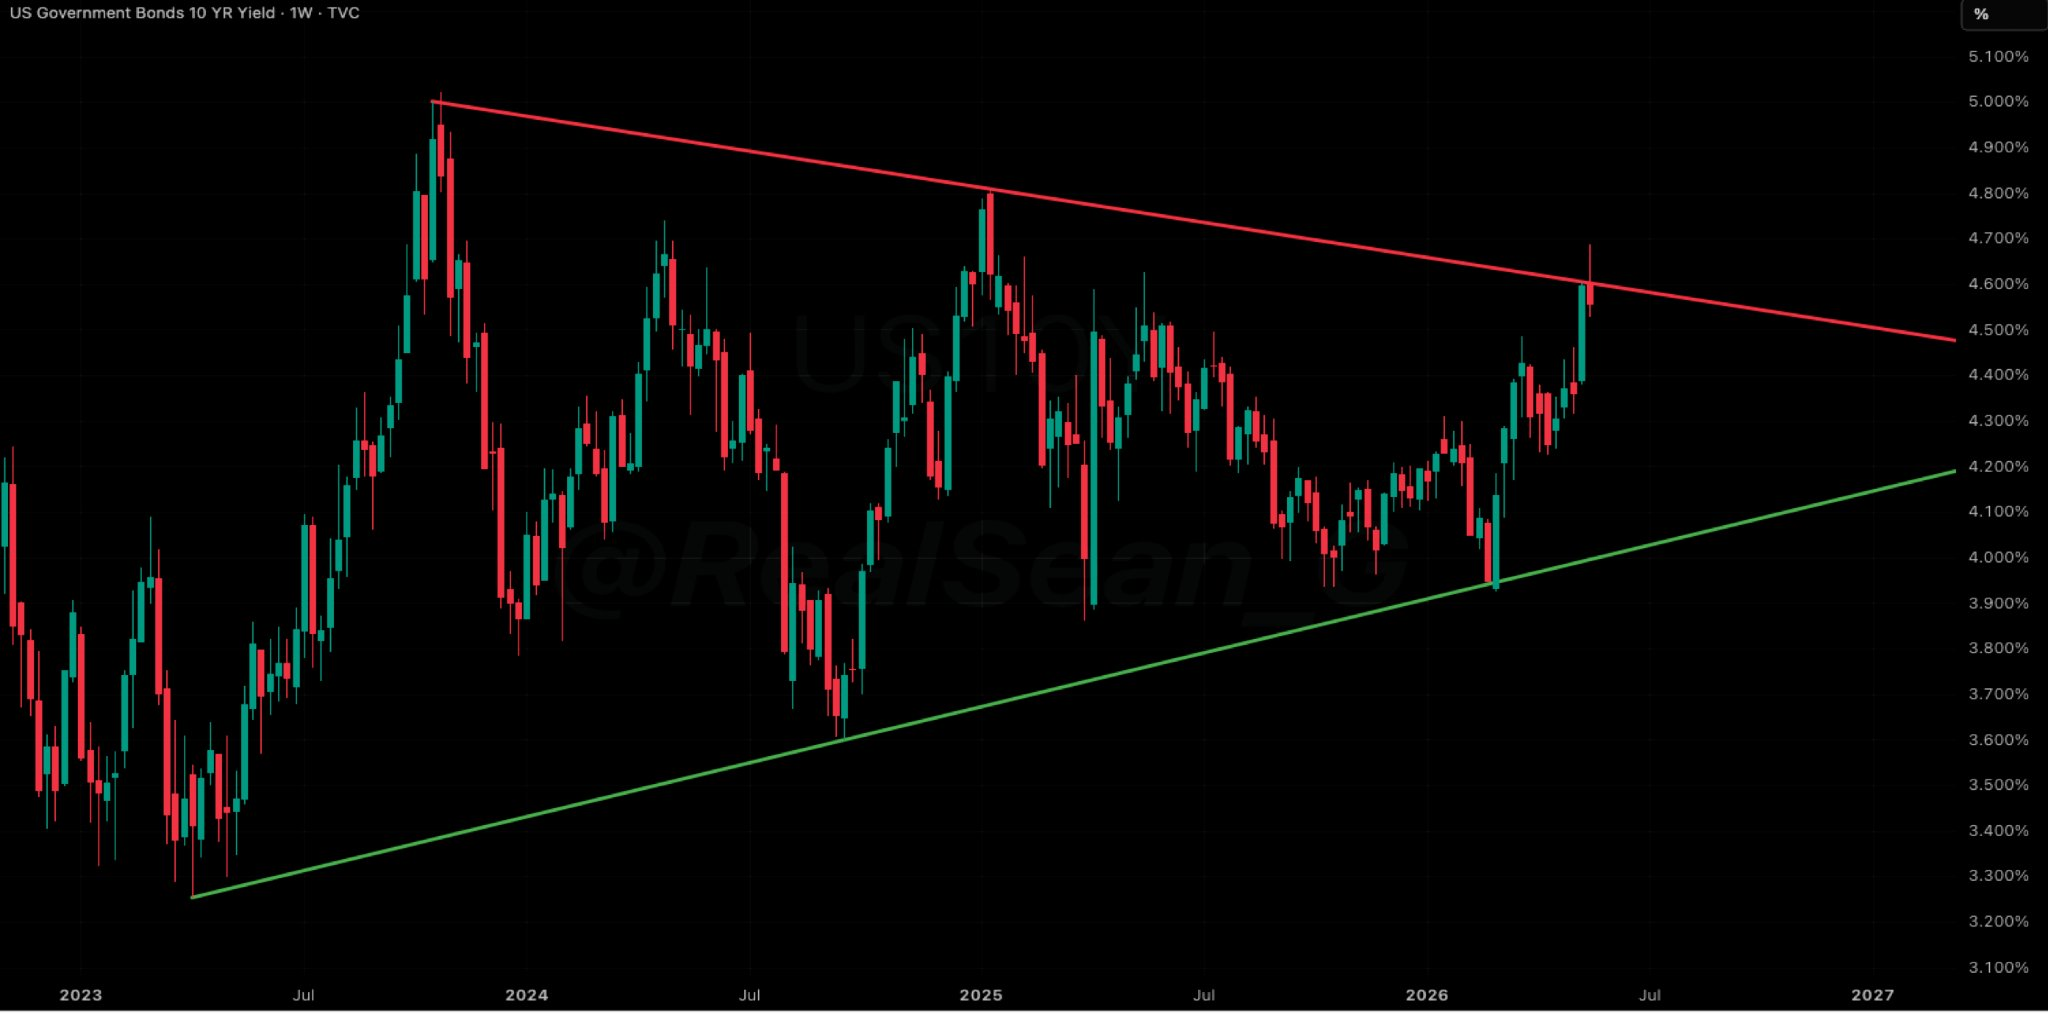
US10Y · —US10Y (U.S. 10-Year Treasury Yield) closed right at the multi-year downtrend resistance line. This is perhaps the only real resistance global long-end yields have left. A sustained breach above opens the door to a test of the 2023 high, after which we could see a repeat of the 1970s-1980s stagflation era.
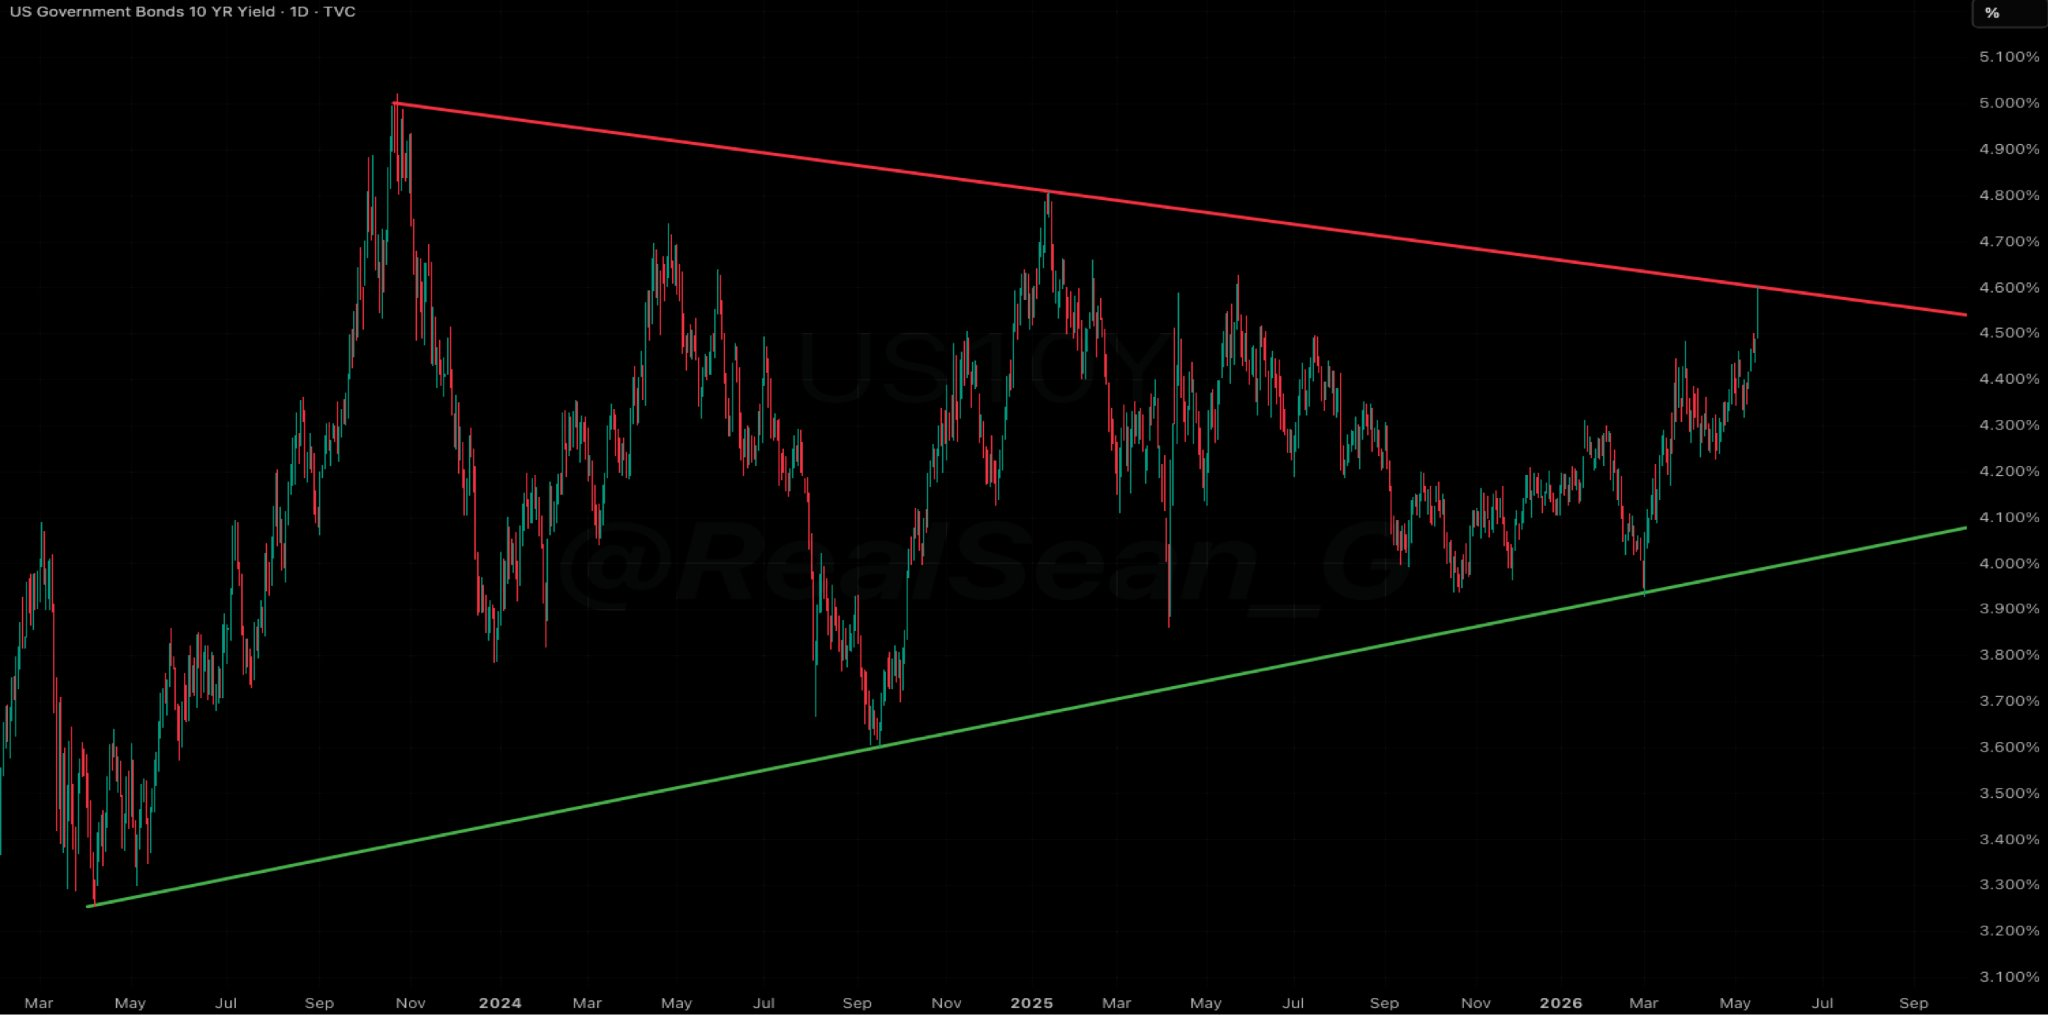
US10Y · —Last week, I mentioned that the US10Y (U.S. 10-Year Treasury Yield) multi-year downtrend resistance line is the only resistance global long-end yields have left. The market tried very hard to defend it this week, and we saw a fakeout. A sustained breach above opens the door to a test of the 2023 high, after which we could see a repeat of the 1970s-1980s stagflation era.
US10Y · —
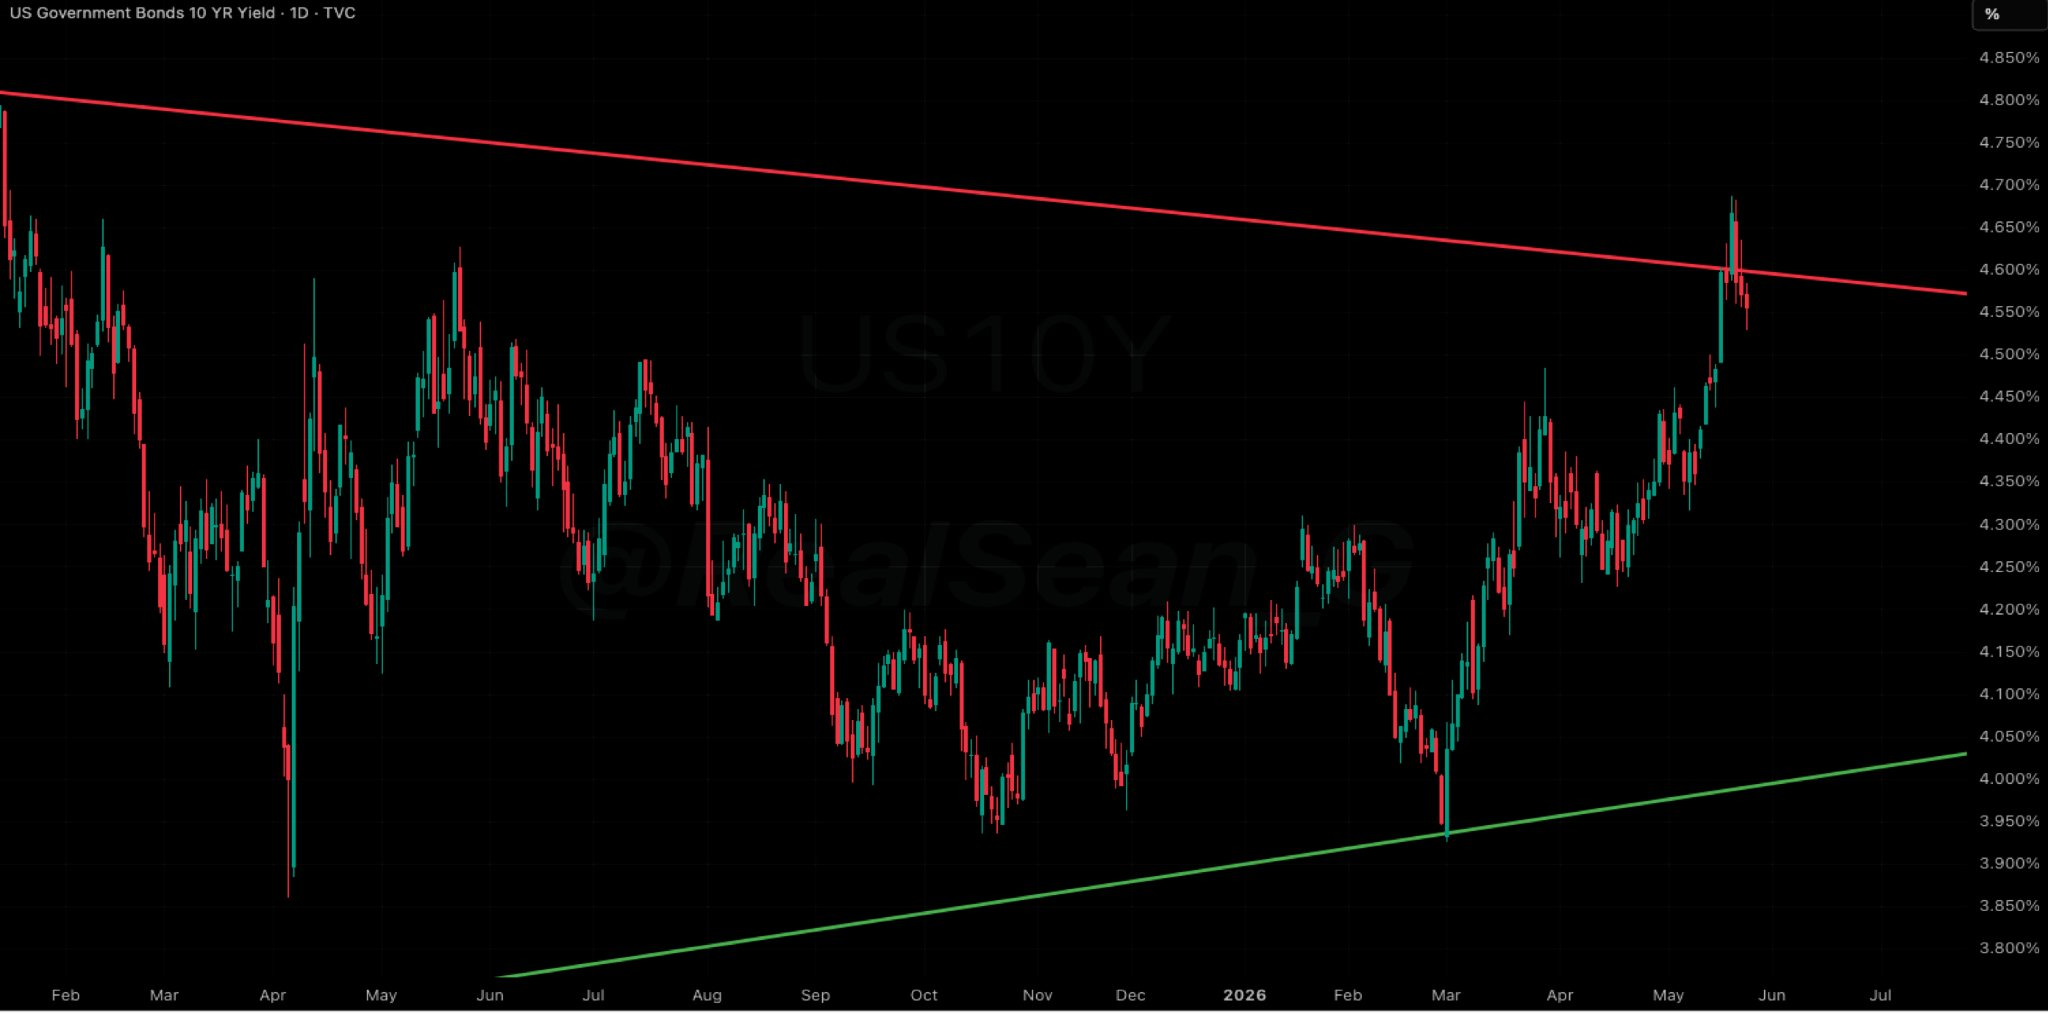
US10Y · —Timely efforts to defend 10Y yields, as this is the most important rate in the world. As mentioned two weeks ago, the US10Y (U.S. 10-Year Treasury Yield) multi-year downtrend resistance line was the only resistance global long-end yields had left, and the administration would try its best to defend it.
We did get the fakeout, as expected. A sustained breach above that resistance would open the door to a test of the 2023 high, after which the market could start pricing a repeat of the 1970s-1980s stagflation regime.
On the downside, the next support sits around the uptrendline. Until that breaks, US10Y should remain range-bound between 4.1% and 4.6%.
US10Y · —
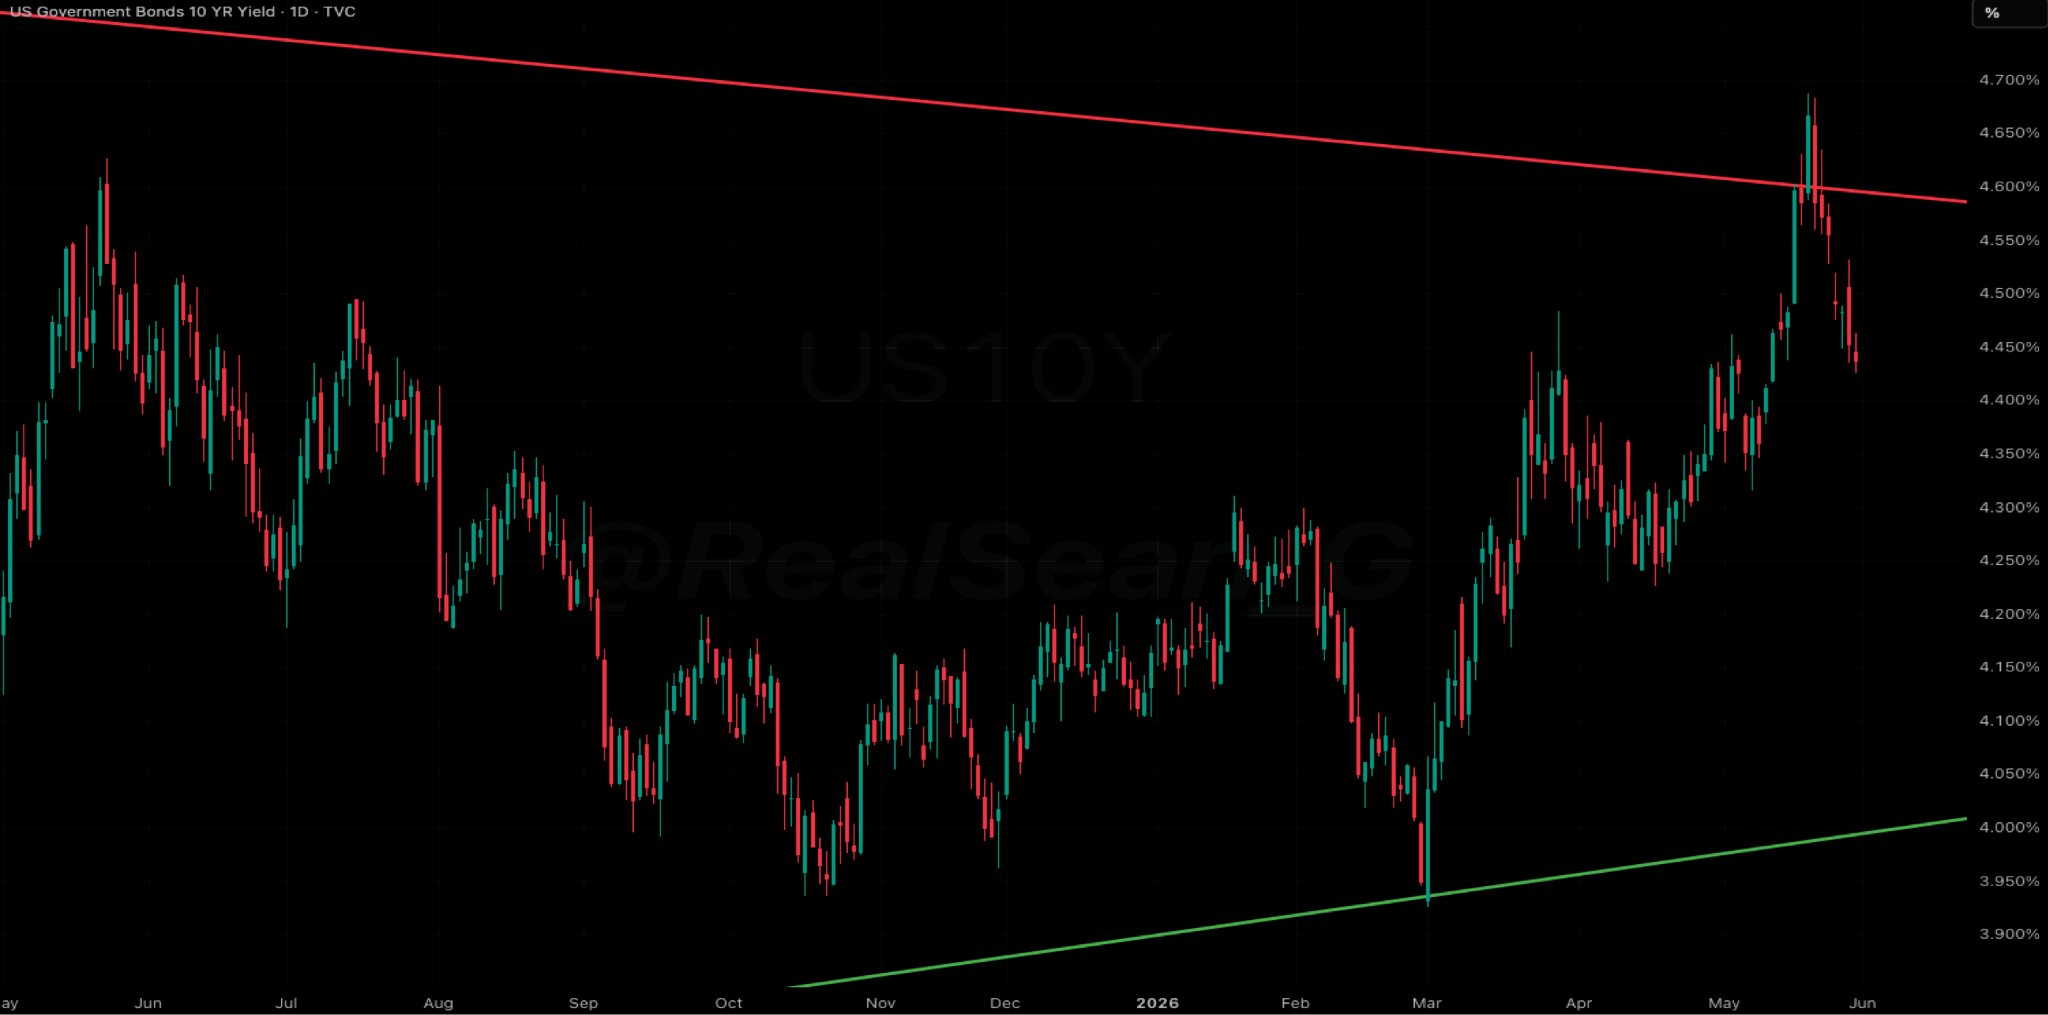
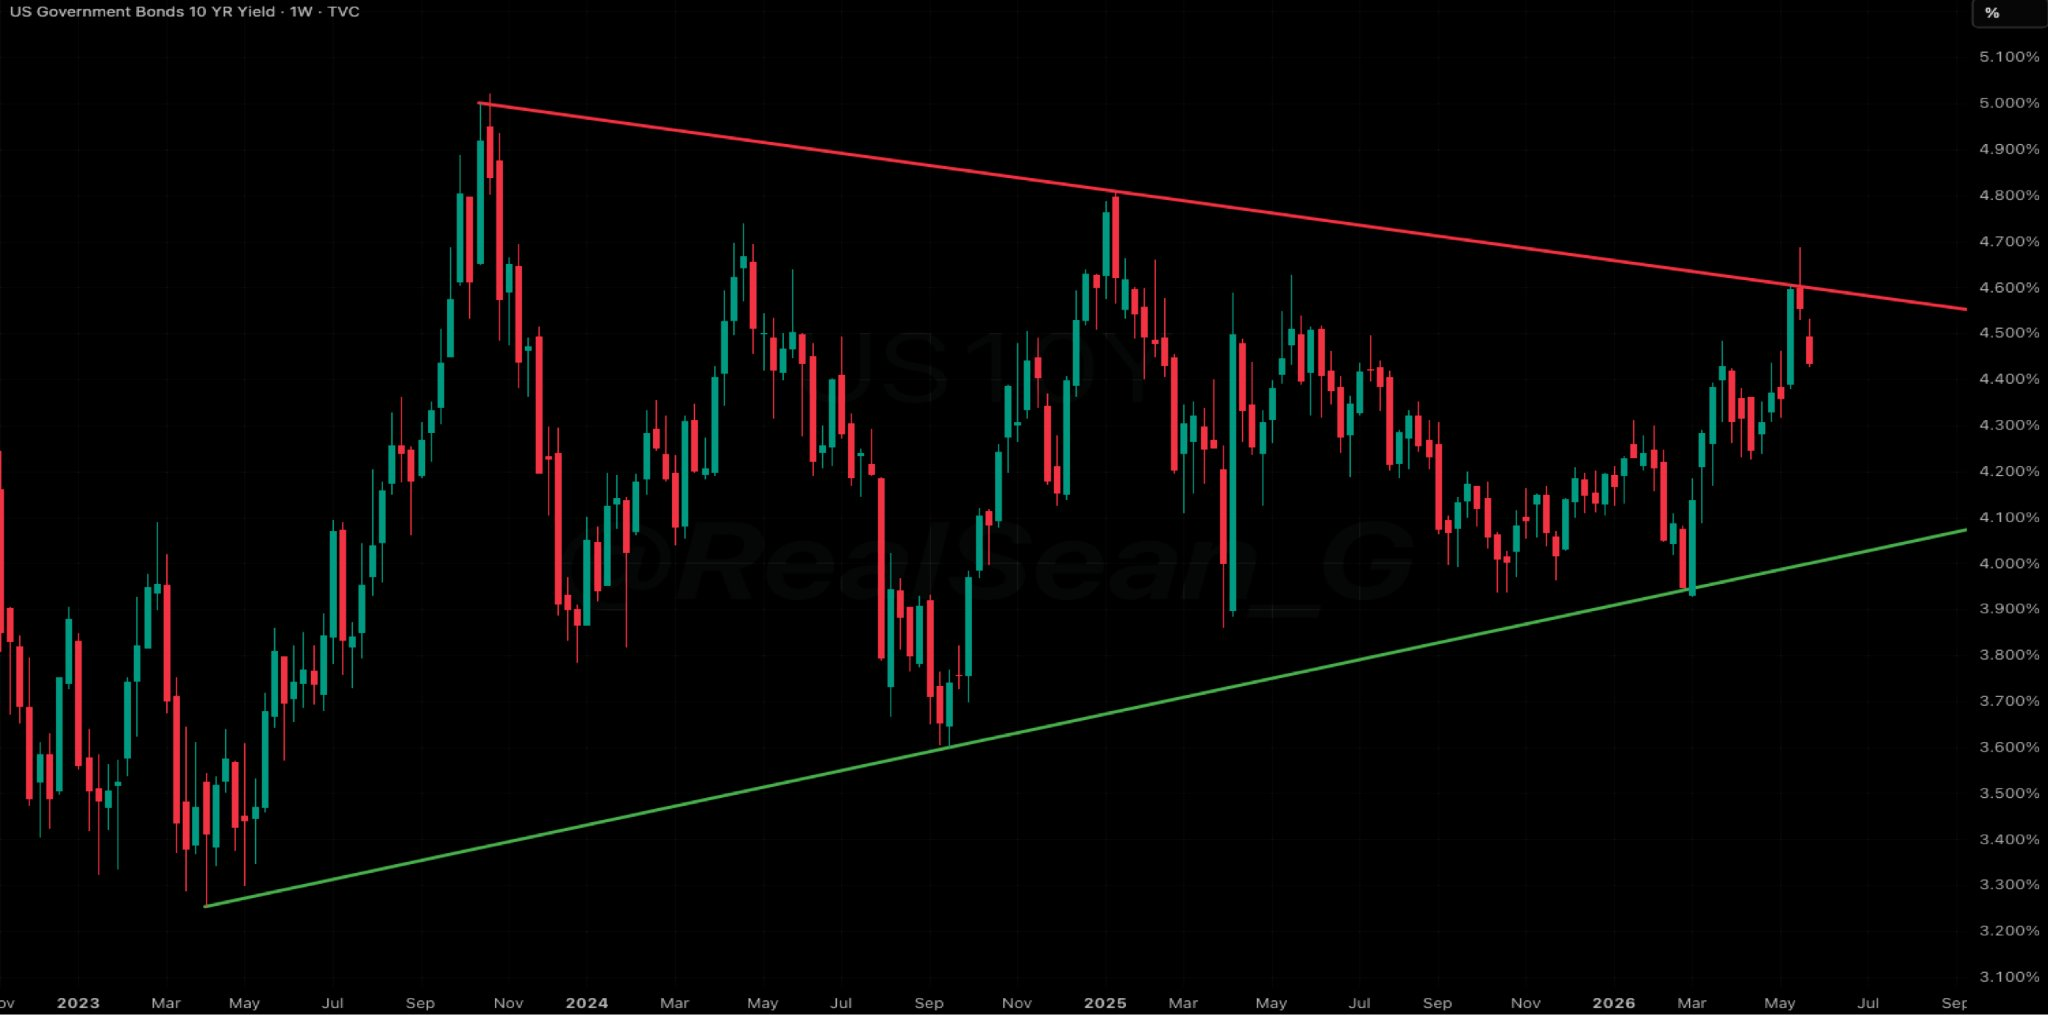
US10Y · —US10Y (U.S. 10-Year Treasury Yield) is still trapped inside a long compression pattern, with lower highs from 2025 and higher lows from the March washout. The next support zone is around 4.05-4.1%. If that holds, 10s stay range-bound and can coil again.

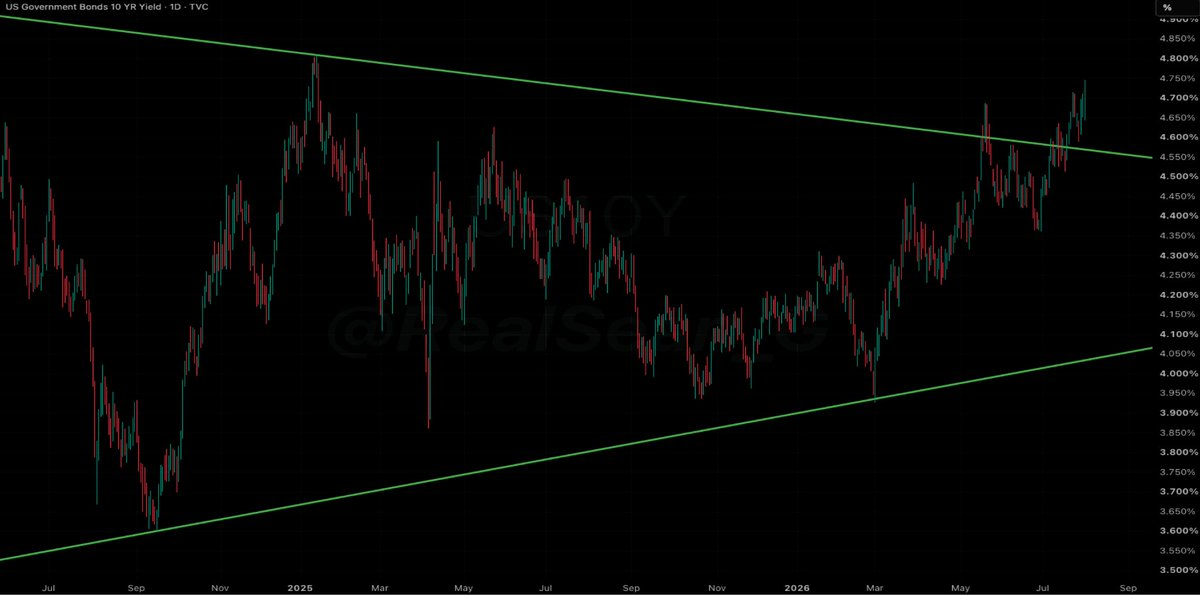
US10Y · —Global long-end yields are on an ominous trajectory. I warned about long-end yields exploding to the upside back in 25Q4, and they're set to only grind higher. In May, referring to the US10Y multi-year descending trendline, I wrote, "This is perhaps the only real resistance global long-end yields have left." That resistance has now broken.
On FOMC day, Warsh, Trump's latest Fed puppet, unsurprisingly held rates steady. Equities initially reversed sharply higher. Trump then tested the waters by threatening to strike Iran. The bond vigilantes slapped Trump in the face. Long-end yields surged, US30Y broke to its highest level since July 2007, and the equity rally was erased into the close. US30Y extended the move later in the week.
That move is very bad for Trump and the U.S. economy. It is also backfiring on his effort to reduce the government's debt-service burden.
Yield trends can run for years, and the recent breakouts in US10Y and US30Y may mark the continuation of the stagflation era I have anticipated for years. In my view, that era began when Powell delayed rate hikes to secure a second term, allowing post-Covid inflation to spiral out of control.
The easing cycle that began in 2024 gave the bond market temporary relief, but that relief is now over. Those resistance levels have given way, and yield trends are extremely difficult to reverse once they begin. The window for Trump to reverse course is closing. If he fails, I can easily see US10Y and US30Y moving into the 6%-7% range over the coming years.
US10Y saw follow-through on last week's breakout above multi-year resistance. As long as it holds above the broken trendline, the path of least resistance remains higher. A sustained move back below it invalidates the breakout.
From other publications
Loading related content…